
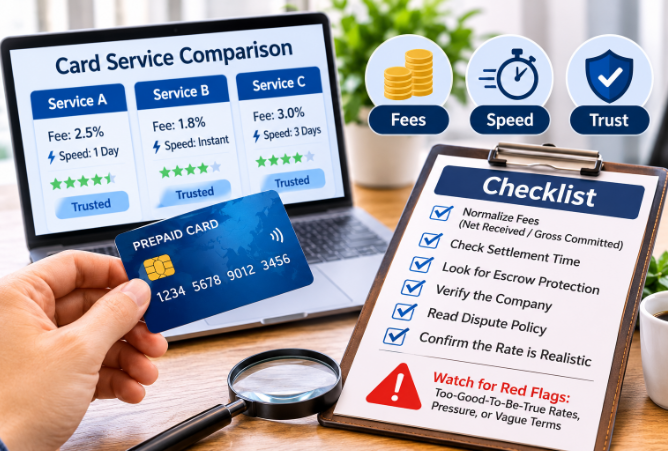
Evaluating Third-Party Card Services: Fees, Speed, And Trust Signals
The financial services layer that sits between consumers and their card balances has grown considerably more crowded over the past decade. Balance aggregators, prepaid issuers, resale marketplaces, payout platforms, and stored-value conversion operators all occupy some part of this space. Most consumers encounter one or another without much basis for judging it, and the marketing across the category is remarkably uniform: fast, easy, secure, trusted. Those words carry no information. This article is about what does.
The framework below applies to any third-party service that touches card or stored-value balances. It is deliberately unglamorous, because evaluating a financial counterparty is a checklist exercise rather than an intuition exercise, and intuition in this domain is systematically miscalibrated by good design.
Fees: Normalize Before Comparing
The single most common consumer error is comparing headline numbers across services that quote fees in different formats. A service might present its charge as a percentage commission, a discount off face value, a flat processing fee, a spread between quoted rates, or some combination. These are not comparable as stated, and the variation is not accidental — format choice is a marketing decision.
The fix is mechanical. Reduce every offer to one number: net amount received divided by gross amount committed. Everything else is noise. Then, separately, note the settlement time in days. Two numbers, universally comparable.
Look specifically for costs that appear downstream of the headline. Withdrawal or transfer fees on the receiving end are the most common. Minimum transaction sizes that strand a remainder are the second. Verification, expedite, and cancellation charges follow. None of these are illegitimate on their own — every operator has real costs — but a service that surfaces them only at the final confirmation screen has told you something about how it treats customers.
A related signal: does the service publish its fee schedule where you can read it before creating an account? Operators confident in their pricing generally do. Operators whose pricing only makes sense in the context of a nearly completed transaction generally do not.
Speed: Understand What You Are Paying For
Settlement speed is a genuine cost driver, not a marketing flourish. An operator that pays out in minutes is taking on risk that an operator paying out in five days has time to verify away. Chargebacks, drained balances, duplicate sales, and identity fraud all become visible over time, and immediate settlement means absorbing those losses rather than screening for them. Faster therefore costs more, everywhere, always.
The consumer question is whether you need the speed. Urgency distorts this judgment badly. Someone in a hurry will pay a substantial premium for hours of acceleration they did not require, because the decision is made in the emotional state that urgency produces. It is worth asking explicitly: what would actually happen if this settled on Thursday instead of now? Frequently the answer is nothing.
Regional context shapes how the speed-versus-cost trade is packaged. What Korean consumers call 카드깡 업체 covers operators structured around direct purchase of card value rather than the brokered-marketplace model more familiar in Western markets, and direct purchase settles faster precisely because the operator absorbs the risk itself. The evaluation criteria transfer regardless of local structure, because the underlying questions are identical everywhere: who holds the code, who holds the money, and what happens when something goes wrong.
Be equally wary of the opposite pattern — a service that is slow and expensive. Delay should buy something, either a lower fee or stronger verification. A service offering neither is not managing risk carefully; it is managing your money carelessly.
Trust Signals That Mean Something
Most visible trust signals are worthless. Badges, testimonials, review counts, and stock photography can all be manufactured in an afternoon. The signals that carry information are structural and harder to fake.
Escrow or staged settlement. Does the process protect both parties, or does it require you to hand over value on the promise of payment? For card codes specifically, which are bearer instruments with no reversal mechanism, this is the single most important question. Any process that requires you to disclose a code before payment is secured is asking you to accept the entire risk of the transaction.
Verification at the moment of transfer. A balance verified last week means nothing. Serious operators check at handover.
Identifiable operating entity. A registered company name, a physical address, and a stated regulatory posture. This does not guarantee good behavior, but its absence is a strong negative signal, and it determines whether you have any recourse at all.
Specific, boring documentation. Terms that describe exact processes, timelines, and dispute handling indicate an operation that has thought about failure cases. Terms consisting of reassuring adjectives indicate one that has not.
Consistent, checkable public history. How long has the operator existed, and does its stated history match anything verifiable?
Red Flags Worth Taking Seriously
Rates materially better than the broad market for comparable value warrant scepticism rather than enthusiasm. Ask what business model supports them. Occasionally the answer is a genuine promotional loss leader; more often it is that payment is not part of the plan.
Pressure and artificial deadlines are a reliable negative signal. Legitimate financial services do not benefit from you deciding in the next four minutes, and their offers do not evaporate.
Requests to move the conversation to a private messaging channel remove every protective mechanism a platform provides. This is nearly always the prelude to a loss.
Vague or shifting explanations of the fee structure, particularly when the number changes between the quote and the confirmation, indicate either disorganization or intent. Neither is acceptable in a counterparty holding your money.
A Short Checklist
Before committing to any third-party card service: normalize the fee to net-received-over-gross-committed; note settlement days; confirm there is an escrow or staged-release mechanism; identify the legal entity behind the service; read the dispute process; and confirm the rate is plausible rather than exceptional.
Six checks, perhaps twenty minutes. That is a modest investment against the class of loss that is essentially unrecoverable — and in a category built on bearer instruments, unrecoverable is the default outcome when something goes wrong.